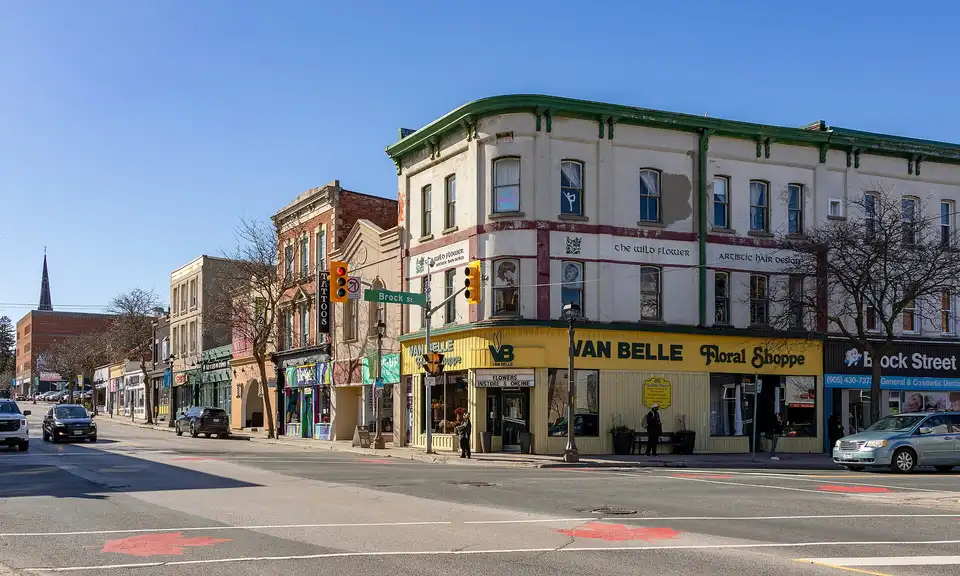

ReverseMortgageWhitby.ca covers reverse mortgages for people who own an older home in downtown Whitby, around Brock Street and Dundas Street. If you’re 55 or over, you can borrow against your home’s value and go on living there. Richard Hopkins, Mortgage Broker, compares every reverse mortgage lender in Canada to find the right fit.
Downtown Whitby: the town’s oldest streets
Whitby took its name in 1848 and was incorporated as a town in 1855 (Whitby Archives). The business centre grew up around the corner of Brock and Dundas.
Older homes are rare in Whitby as a whole. Only about 8% of the town’s homes were built in 1960 or earlier, according to the 2021 Census (Statistics Canada). Many of the town’s older streets are downtown.
Daily life here is close at hand. The Centennial Building is home to the Whitby Courthouse Theatre. Lynde House Museum, the Central Library with the Whitby Archives, and a farmers’ market from May to October are all part of downtown (Town of Whitby).
Homes in the Werden’s Plan heritage district
The Werden’s Plan Neighbourhood Heritage Conservation District covers 250 properties. The Town calls it the area with the greatest number of historic residential streetscapes downtown, and updated its plan by By-law 8280-26 (notice of passing May 8, 2026) (Town of Whitby).
Owners in the district need a heritage permit before doing proposed work. Plan your repairs with that step in mind, especially for accessibility changes such as a ramp or a wider doorway.
Being in the district doesn’t stop a home from qualifying. The appraiser values it like any other home, by comparing recent sales nearby.
Some owners receive the Town’s Heritage Property Tax Rebate, which gives back 40% of the Town and education taxes on the heritage part of the assessment. That rebate requires an easement agreement with the Town, and any mortgage lender must agree to rank behind it (Town of Whitby). Tell Richard about it in your first email.
Older homes and the appraisal
The home’s condition is part of every approval. The appraiser looks at the house during one visit and reports its value to the lender.
Sometimes a repair you’ve already booked can be included in the mortgage through a holdback, money the lender holds back until the work is finished. Keeping up the home stays your responsibility after closing, along with property tax and insurance.
What downtown values mean for you
Downtown Whitby’s median sale price was $745,500 from April to June 2026, across 32 sales. Homes sold for 102% of their asking price on average (TRREB, Q2 2026).
At age 70, you could qualify for up to about 52.85% of your home’s value. On a $745,500 home, that’s a ceiling of about $394,000.
Older owners qualify for more. Try your own age and value in the Whitby reverse mortgage calculator, and see the Whitby home prices guide for the wider market.
Any mortgage you still owe is paid off first from the same money. You choose how much to take, and interest is charged only on what you take.
Staying, or moving to something smaller
Some downtown owners weigh a move against staying. A new seniors’ building at 409 Centre St S will have 30 affordable units (14 affordable and 16 rent-geared-to-income), replacing an older building, with completion expected in spring 2027 (CMHC, July 31, 2026).
Selling a home has its own costs, and the cost of downsizing in Whitby lists the main ones. If care needs grow, long-term care in Whitby explains the homes and the monthly fees.
Health care nearby matters too. Whitby Hospital at 300 Gordon St, part of Lakeridge Health, offers dialysis, complex continuing care and geriatric rehabilitation, but it has no emergency department (Lakeridge Health).
When the mortgage comes due
The mortgage comes due when the home is sold, when the last borrower permanently moves out, or when the last borrower passes away. A permanent move into long-term care counts as moving out.
A stay at Whitby Hospital for rehabilitation, or any other temporary hospital stay, does not make the mortgage due. If you and your spouse are both borrowers, the survivor keeps living in the home with nothing to repay.
When the time comes, your family controls the sale and keeps every dollar above the balance. The lender never owns your home.
The promises that protect you
There are no required monthly mortgage payments. Property tax, home insurance and upkeep remain yours.
You can never owe more than your home is worth (its fair market value) when the mortgage comes due, as long as taxes, insurance and upkeep are kept up. Downtown Whitby owners get this protection, typically called the no negative equity guarantee, from every lender.
Over the years, interest builds up on the balance. Rising downtown Whitby home prices can make up for part or all of it, so your equity is not certain to shrink.
Richard also arranges home equity lines of credit, refinances and regular mortgages. You get the option with the best overall value for you, even if it’s not a reverse mortgage.
Property tax help for downtown seniors
Whitby’s low-income seniors’ rebate is open to owners 65 and over who receive the Guaranteed Income Supplement, with applications due by December 31 each year. The Town’s tax deferral is closed until the next province-wide reassessment. The Whitby property tax guide for seniors covers both.
Streets and places in Downtown Whitby
Wherever your home sits in Downtown Whitby, the help works the same way. A few of the places it covers:
- Werden's Plan Neighbourhood
- Brock Street
- Dundas Street
- Centre Street South
- Byron Street
Landmarks you'll know
- Centennial Building, home of the Whitby Courthouse Theatre
- Lynde House Museum
- Whitby Central Library and the Whitby Archives
- Whitby Farmers' Market, May to October
- The Promenade at Brock, Byron and Mary Streets
- The Werden's Plan Neighbourhood Heritage Conservation District (250 properties)
How Richard works with Downtown Whitby homeowners
Downtown Whitby homeowners work with Richard by email, phone and video call, from home. You never need to visit an office. The appraiser comes to your home once. For the independent legal advice, you meet your own lawyer, and you can choose one close to home.
Home values in Downtown Whitby
Downtown Whitby had 32 sales from April to June 2026, with an average price of $744,319 and a median of $745,500; homes sold at 102% of their asking price on average. On that median, a homeowner aged 70 could qualify for up to about $394,000 (52.85% of the value). Treat that as a ceiling: the appraisal of your own home sets the real figure.
Source: TRREB Community Housing Market Report, Durham - Whitby, Q2 2026
What Downtown Whitby homeowners use the money for
- Paying for care at home: Public care first, then Town supports, then a way to pay for private hours without a monthly mortgage payment.
- Renovating to stay in your home: Main-floor bedrooms, walk-in showers and stair lifts for Whitby family homes, and a way to pay without monthly payments.
- Adding a suite for family: Town rules, fees and deadlines for a basement apartment or garden suite, and a way to pay for the build without monthly payments.